
Does Your Homeowners Insurance Cover an EV Charger or Powerwall?
How homeowners insurance usually classifies an EV charger
Most homeowners policies split protection into a few parts. The two that matter most here are dwelling coverage and personal property coverage.
The practical difference is that each part has its own limit and sometimes its own deductible rules. A charger on an attached garage wall generally rides along with your main dwelling coverage.
- Dwelling coverage: Protects the structure and things permanently attached to it. A hardwired wall-mounted charger, such as a Tesla Wall Connector, is generally viewed as a permanent fixture, much like a water heater or built-in lighting.
- Personal property coverage: Protects movable belongings. A portable charging cable or a mobile charger that simply plugs into an outlet is more likely to fall here.
- Other structures coverage: If your charger is mounted on a detached garage or carport, that separate building is typically handled under this part of the policy.
How a Powerwall is typically treated
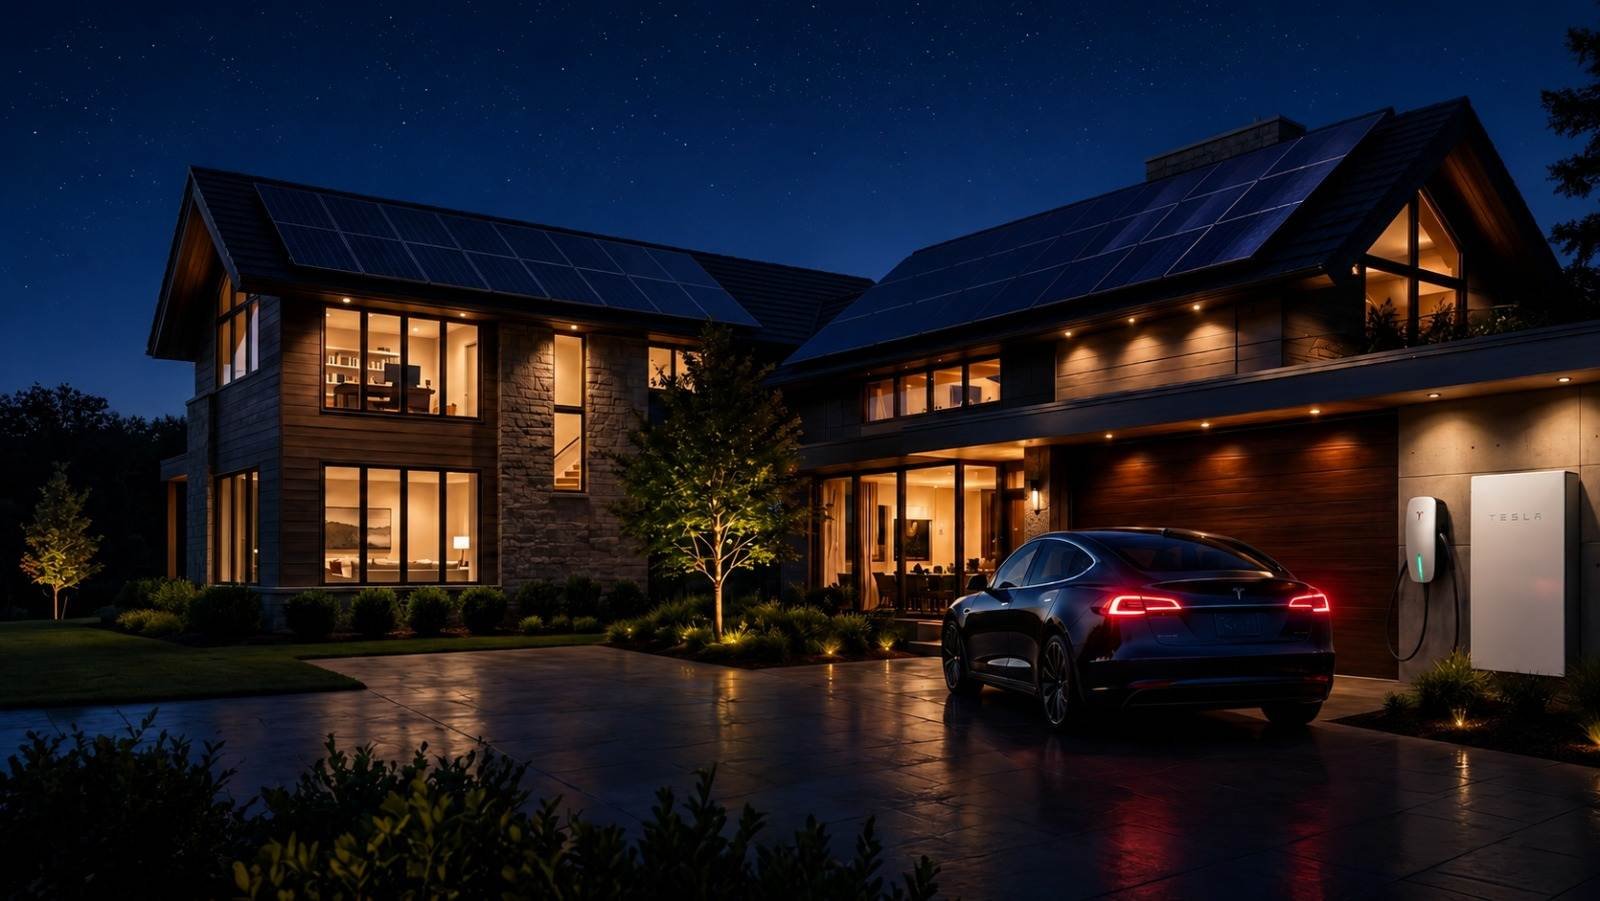
A Powerwall is a permanently installed home battery that is wired into your electrical system, usually mounted in a garage or on an exterior wall. Because it is attached and integrated with the home, insurers commonly treat it as part of the dwelling, similar to solar equipment or a whole-home generator.
That said, batteries are newer to many underwriters than chargers are. Some insurers ask whether you have a home battery, want the make and model, or want to know where it is located. A few may handle it differently than a standard fixture. The only reliable way to know is to ask your insurer directly and get the answer in writing.
What is commonly covered
Policies differ, but covered events for a properly installed charger or battery commonly include:
If a covered event damages the equipment, the policy generally pays to repair or replace it, subject to your deductible and coverage limits. Some policies pay replacement cost, while others pay actual cash value, which accounts for depreciation. That distinction can matter a lot for equipment that has been in service for years.
- Fire, including a fire that starts elsewhere in the home
- Lightning
- Windstorm and hail
- Theft and vandalism
- Falling objects, such as a tree limb
- Certain kinds of accidental damage, depending on the policy
What is commonly not covered
Even with solid coverage, some situations tend to fall outside a standard homeowners policy:
Warranty and insurance are separate. A manufacturer warranty addresses defects in the product. Insurance addresses damage from covered events. Neither replaces the other.
- Normal wear and tear or manufacturer defects. A charger or battery that fails on its own is usually a warranty matter, not an insurance claim.
- Flood and earth movement. These typically require separate policies or endorsements.
- Vehicle impact. If a car backs into the charger, the claim may involve your auto policy instead, depending on the circumstances.
- Power surge damage. Some policies cover it and some limit it, so the wording matters.
- Damage tied to unpermitted or improper work. An insurer may push back on a claim if the equipment was not installed to local requirements or by a qualified professional.
- Lost savings or stored energy. Policies generally do not reimburse you for the value of electricity or backup capacity you could not use.
Why professional, permitted installation matters for coverage
Insurers care about how electrical equipment is installed, because improper wiring is a real fire risk. A licensed electrician handles load calculations, breaker sizing, wire gauge, grounding, and local permits and inspections. Having that paperwork on file gives you documentation if you ever need to show an adjuster that the equipment was installed correctly.
Charge Home Solutions works through a Tesla-certified network of licensed and insured electricians, so the work is done by qualified professionals and can be documented. For the full step-by-step process on how Tesla equipment is installed, see our Tesla installation hub at chargehomesolutions.com/tesla-installation-hub/.
Will adding a charger or Powerwall change your premium?
It can, but not always. Some insurers see no change for a standard charger. Others adjust the policy if the home's value increases or if a battery is added. Some homeowners also find that a battery, by supporting the home during outages, is viewed favorably, though discounts are not something to assume.
Because the answer varies by insurer and location, the safest approach is to notify your insurer when you add significant equipment. Failing to disclose a major home improvement can create gaps if you need to file a claim, and updating the dwelling coverage amount helps ensure you are not underinsured.
Questions to ask your insurance agent
Before or right after installation, consider asking:
1. Is a hardwired EV charger covered under dwelling coverage on my policy? 2. Is a Powerwall or other home battery covered, and are there any special conditions or exclusions? 3. Is my equipment covered at replacement cost or actual cash value? 4. Does my policy cover power surge damage to this equipment? 5. Do I need to report the installation, and will it affect my premium? 6. If my charger is on a detached structure, what limit applies? 7. Do you need a copy of the permit, invoice, or inspection record?
Special situations: renters, HOAs, and rentals
If you rent, your landlord's policy typically covers the building and any fixtures, while your renter's policy covers your own belongings. Equipment you own and take with you may fall under your personal property coverage. In a condo or HOA community, the master policy and your individual policy may split responsibility differently, so check both. If you own a rental property with a charger, a landlord or dwelling-fire policy may handle it differently than a standard homeowners policy.
Keep your documentation ready
If you ever file a claim, records make the process smoother. Keep these together:
With the right installer and a quick conversation with your agent, you can add a charger or battery with confidence about how it is protected.
- The installation invoice and equipment model and serial numbers
- Permit and inspection records, where applicable
- Photos of the installed equipment
- Your electrician's license and insurance details
- Any written confirmation from your insurer about coverage
Book your free in-home estimate
Ready to move forward? Charge Home Solutions matches you with a licensed, insured, Tesla-certified electrician in your area, with a free in-home estimate and no obligation.
Request your free estimate at chargehomesolutions.com/request-service or call 888-995-6044.
Frequently asked questions
Often yes. A hardwired charger is generally treated as a permanent fixture and falls under dwelling coverage for covered events like fire or lightning. Confirm the specifics with your insurer, since policies vary.
A Powerwall is commonly treated as part of the dwelling because it is permanently installed and wired into the home. Some insurers have their own requirements for batteries, so ask your agent to confirm in writing.
It is generally a good idea. Reporting a significant home improvement helps ensure your coverage amount is accurate and can prevent surprises during a claim. Your insurer can tell you whether it affects your premium.
It depends. Damage caused by a vehicle may fall under your auto policy rather than your homeowners policy, depending on the circumstances and your coverage.
No. A warranty addresses product defects, while insurance addresses damage from covered events such as fire or theft. They serve different purposes.
It can. Insurers may question claims involving unpermitted or improper electrical work. Using a licensed, insured electrician and keeping permit records helps document that the work was done properly.
Related guides
How to Set a Charge Limit to Protect Your EV Battery at Home
You set an EV charge limit in your car's touchscreen or the manufacturer's mobile app, usually with a slider or percentage setting under the charging menu. For daily driving, many automakers suggest l
Read article →Federal Tax Credits for Home EV Chargers and Batteries Explained
Two federal credits have covered home charging and battery projects: the Alternative Fuel Vehicle Refueling Property Credit (Section 30C) for EV chargers, and the Residential Clean Energy Credit (Sect
Read article →Solar Panels, Battery, and EV Charger: Which Should You Install First?
For most homeowners who already drive an electric vehicle, the home EV charger should go in first, because it delivers a benefit every single day and usually needs the smallest project. If you do not
Read article →Net Metering and Powerwall: How They Work Together
Net metering and a Tesla Powerwall work together by giving your solar energy two places to go: into your home battery, or out to the grid for a bill credit. Net metering credits you for surplus solar
Read article →Can a Powerwall Be Installed in a Cold Climate Garage?
Yes, in most cases a Tesla Powerwall can be installed in a cold climate garage. Powerwall is designed for indoor and outdoor placement and has built-in thermal management, so an unheated garage in a n
Read article →Powerwall Maintenance: What Homeowners Should Check Each Year
A Tesla Powerwall is designed to need very little physical maintenance, but it still pays to run a simple check once a year. The useful yearly review is mostly about the things you can see and confirm
Read article →